Custom AI agent · Finance
AI Vendor Payment Verification Agent
Verify vendor payment details before money moves.
Compare vendor, invoice, and payment-change evidence while routing discrepancies to authorized finance review.
- Less manual checking across vendor records, invoices, and payment instructions
- More consistent visibility into changed, incomplete, or conflicting payment details
- Clearer review queues for authorized finance and procurement owners
Starting at $300 USD/month
Starting price is $300 USD/month for a tailored solution. Your final proposal defines the scope, deliverables and payment terms. Additional integrations, usage, hosting and ongoing support are scoped and priced before work begins.
What is an AI vendor payment verification agent?
An AI vendor payment verification agent helps finance and procurement teams organize checks around supplier identity, invoice context, and payment instructions before a payment is released. It compares approved vendor records with configured invoice, purchase-order, bank-detail, contact, and change-history evidence, then surfaces discrepancies or risk signals for an authorized reviewer. Tranki configures the workflow around your vendor master, segregation of duties, change controls, approval thresholds, communication channels, and audit requirements. The agent prepares a traceable verification packet; it does not authenticate a bank account by itself, approve a payment, determine fraud, or replace independent callback and treasury controls.
What it can verify
Compare vendor evidence
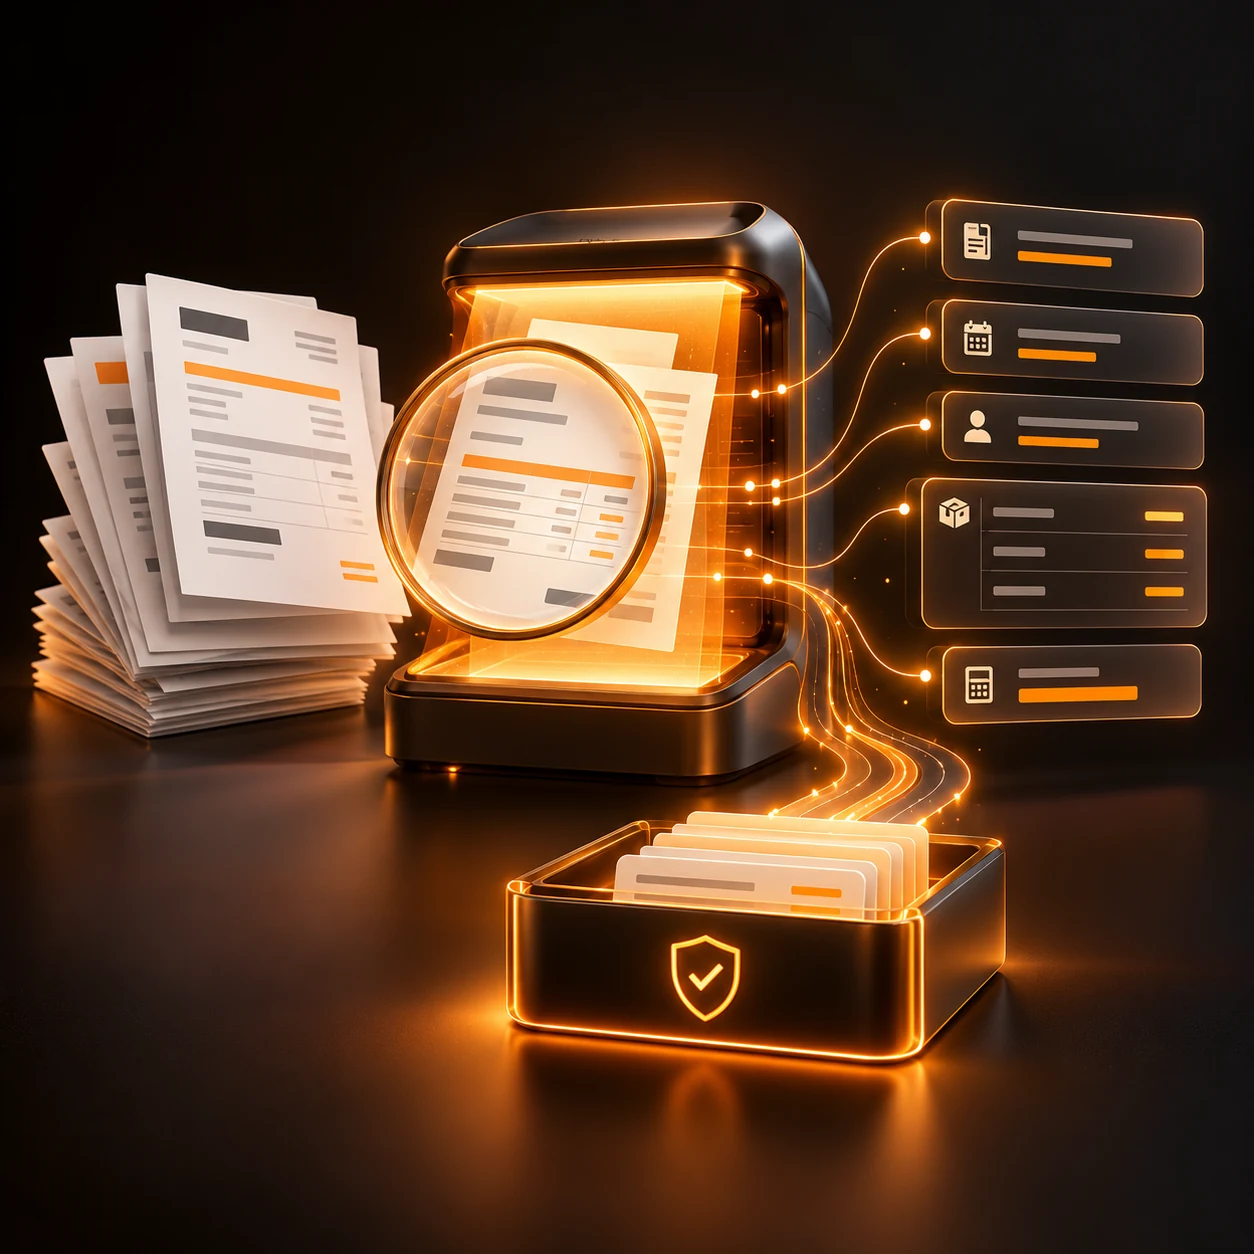
Link approved vendor-master data, invoice details, purchase orders, contracts, payment instructions, contact records, and change history using stable identifiers and permitted sources.
Surface payment-detail changes
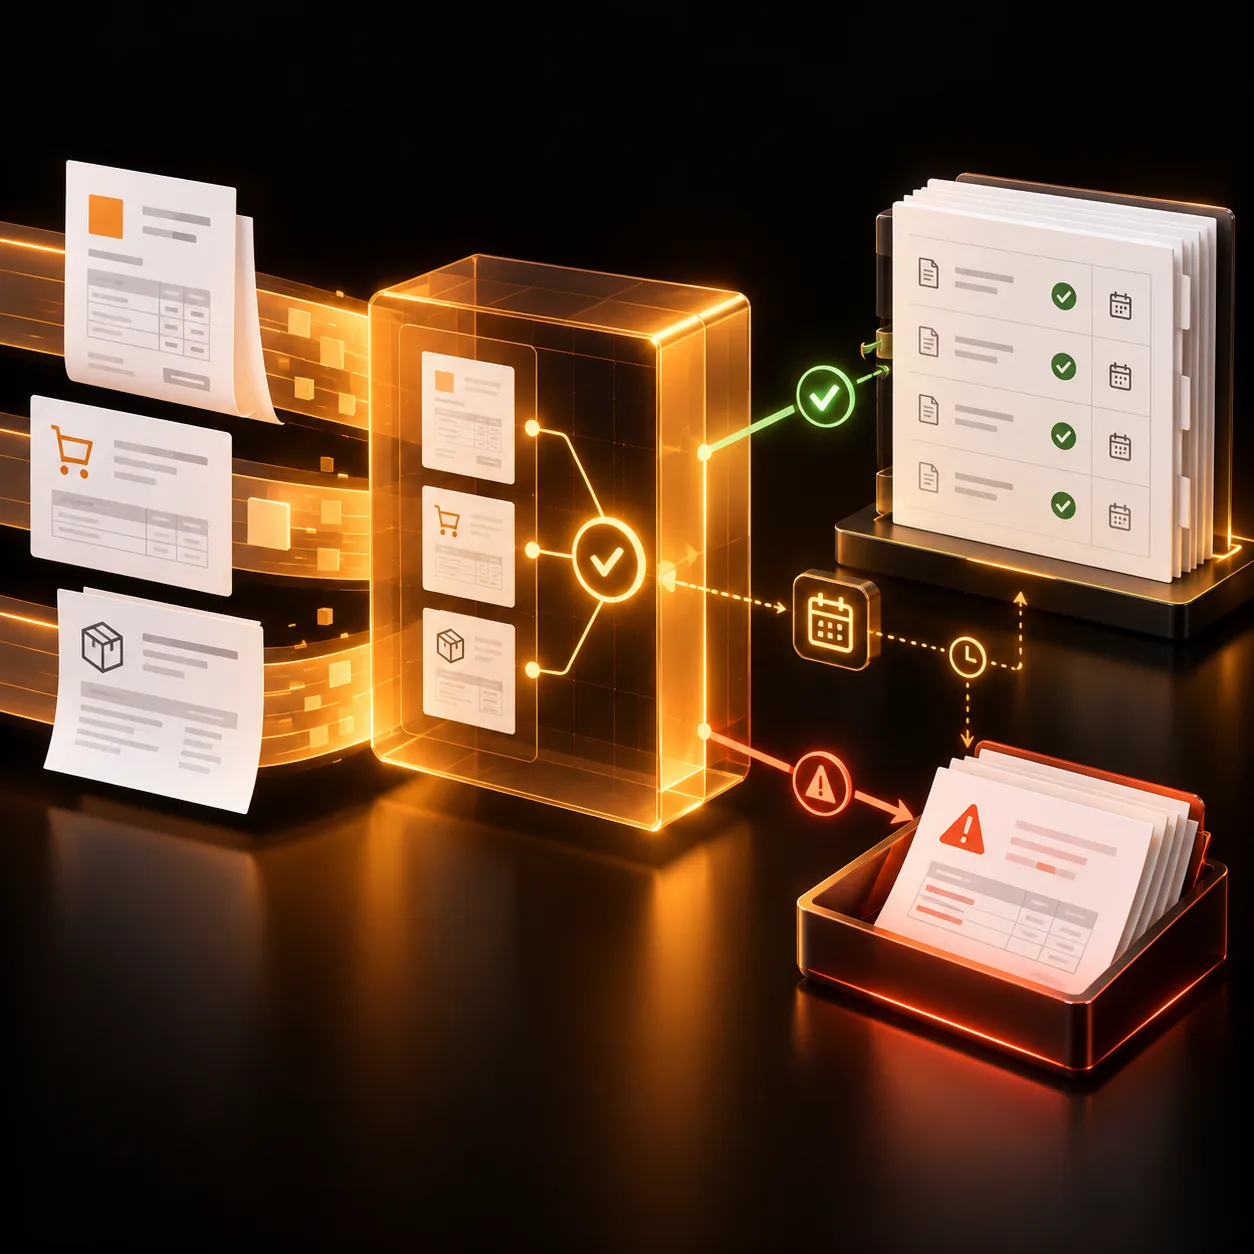
Flag new or changed bank details, mismatched legal names, address or contact differences, unusual request channels, missing approvals, duplicate records, and other configured review conditions.
Preserve the verification trail
Record source references, timestamps, change context, checks performed, open questions, and reviewer ownership without exposing sensitive payment data beyond the authorized workflow.
Route controlled confirmation
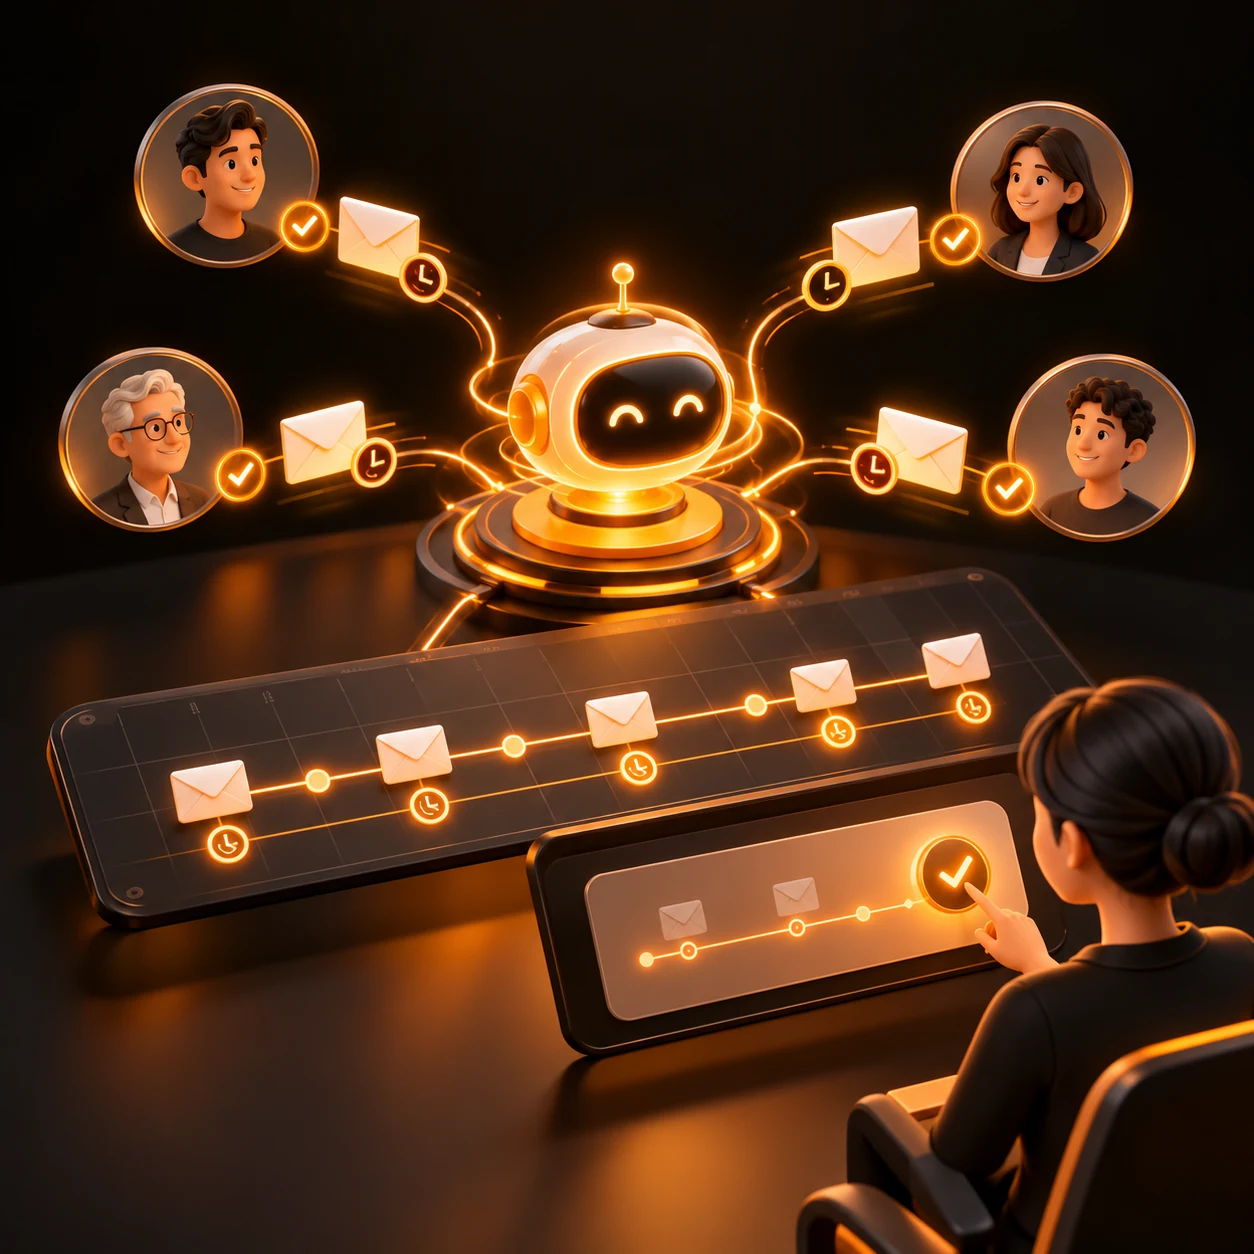
Deliver a focused packet to procurement, AP, treasury, or the designated approver and keep the final confirmation and payment decision under human control.
Where it can help
New vendor onboarding
Organize identity, tax, contract, and payment evidence for a new supplier before the vendor becomes eligible for the approved payment workflow.
Bank-detail change review
Compare change requests with current records, required approvals, and independent confirmation steps before an authorized owner decides what to do.
Invoice payment controls
Check invoice and order context against the vendor record and route inconsistencies, duplicates, and unusual instructions to the right reviewer.
How it works
A step-by-step workflow your team can review before launch.
1. Define verification policy
Tranki maps vendor identifiers, accepted sources, change thresholds, independent confirmation steps, segregation of duties, escalation rules, retention, and approval ownership.
2. Gather approved records
The agent reads permitted vendor, invoice, order, contract, contact, payment, and change-history evidence while preserving source IDs and access boundaries.
3. Compare and flag
It checks configured fields and history, separates confirmed facts from risk signals, and records why a case needs confirmation or review.
4. Route to an authorized owner
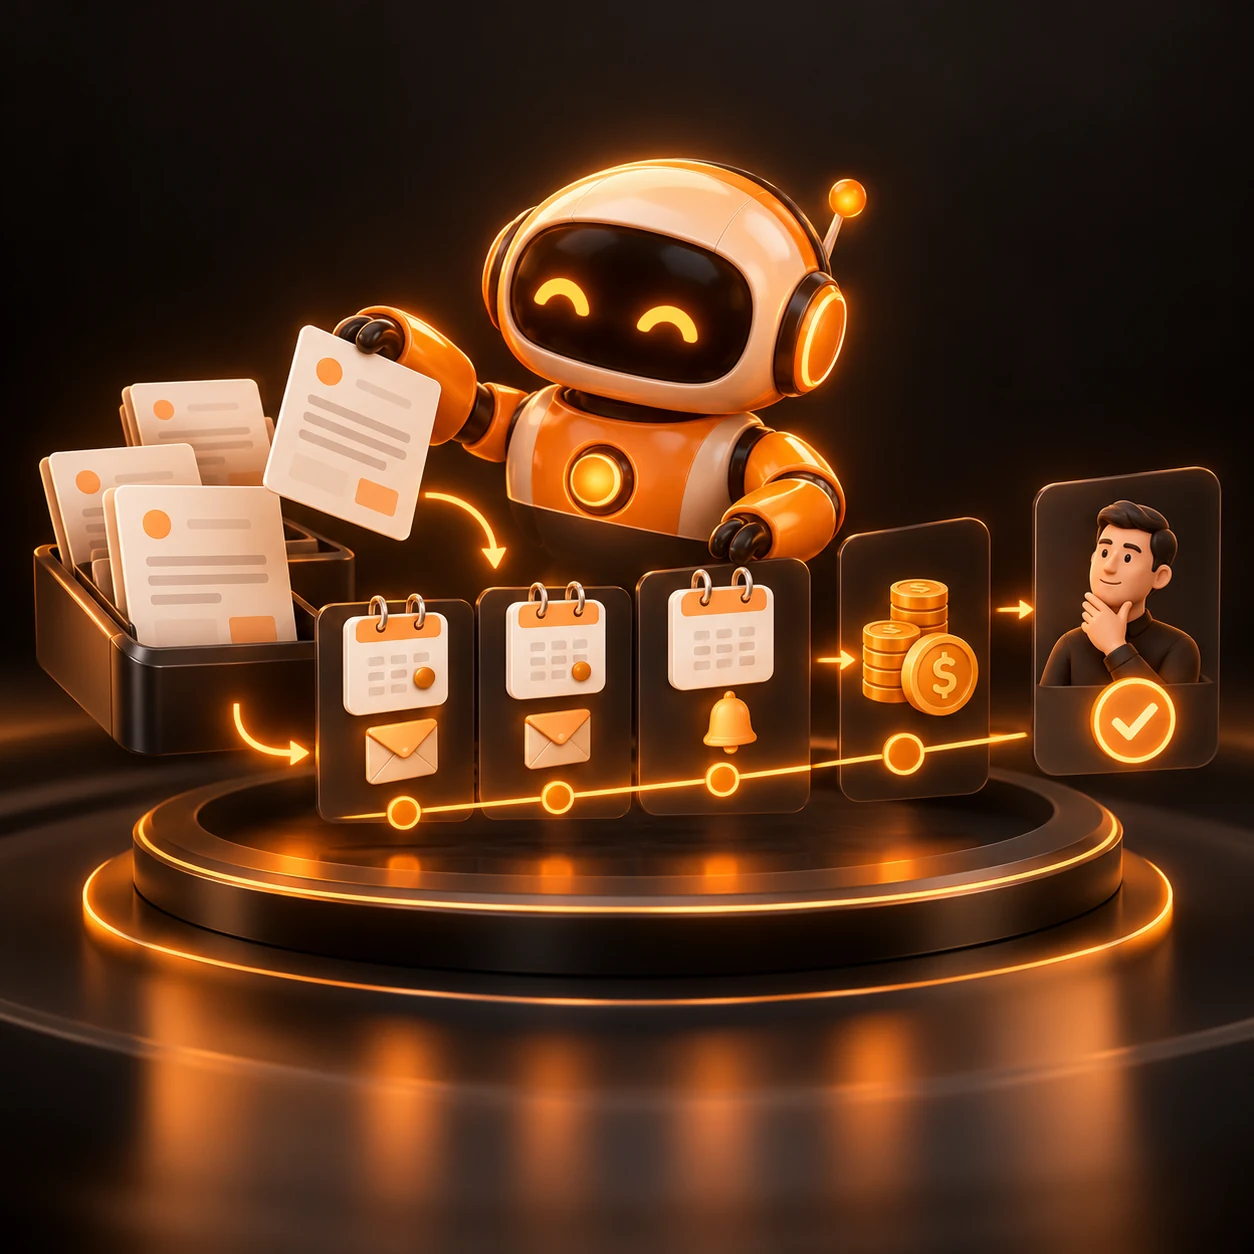
A structured verification packet goes to procurement, AP, treasury, or the approver. Independent confirmation and final payment action remain outside the agent.
Built around your business
What we configure
- Vendor identity fields, legal-name and address matching, bank-detail change rules, invoice and purchase-order links, duplicate signals, approval thresholds, and risk categories
- Independent callback or confirmation workflow, reviewer roles, escalation timing, communication restrictions, redaction, retention, audit fields, and payment-release separation
- Connections to approved ERP, vendor master, AP, procurement, treasury, contract, document, email, or spreadsheet systems using least-privilege access
What we need from you
- Current vendor-master policy, onboarding and change procedures, payment approval matrix, independent confirmation rules, escalation owners, and retention requirements
- Approved access to vendor, invoice, order, contract, payment, contact, approval, and change-history systems with stable identifiers
- Representative new-vendor, unchanged, changed-bank-detail, duplicate, incomplete, mismatched, urgent, and disputed cases for testing
Clear boundaries before launch
What it will not do
The agent does not authenticate a bank account, approve a vendor, release a payment, determine that a transaction is fraudulent, override segregation of duties, alter vendor or ledger records, or replace independent callback, treasury, legal, or security controls. It should not treat an email or invoice as sufficient confirmation of changed payment details, expose full bank information unnecessarily, or suppress an exception because a request is urgent. Suspicious, high-value, disputed, or ambiguous cases require authorized human investigation.
How success is measured
Track verification turnaround, field-match accuracy, reviewer correction rate, change-detection coverage, duplicate and false-positive rates, exception age, independent-confirmation completion, source-reference coverage, manual checks avoided, and the percentage of payment changes with a documented approval trail. Periodically sample outputs across suppliers, regions, currencies, channels, and change types against the underlying records.
Frequently asked questions
What does an AI vendor payment verification agent do?
It compares approved vendor, invoice, order, and payment-change evidence, surfaces discrepancies or risk signals, and routes a traceable packet to an authorized reviewer.
Can it approve a vendor or release a payment?
No. It organizes evidence and flags conditions. Vendor approval, independent confirmation, and payment release remain controlled human actions.
Can it review bank-detail change requests?
Yes, it can compare the request with approved records and configured change controls, then route the case for independent confirmation and authorized review.
Does it determine whether a request is fraud?
No. It can surface configured risk signals and inconsistencies, but qualified security, finance, or legal personnel investigate and decide the response.
What if a supplier asks for urgent payment changes by email?
The workflow can flag the channel and urgency, preserve the request context, and require the independent confirmation step defined by your policy rather than treating the message as proof.
Can it connect to an ERP or vendor master?
Potentially, subject to the approved system, permissions, supported integration method, security review, and final implementation scope.
What is included in the $300/month starting price?
The starting price covers a scoped, tailored solution. The final proposal defines the verification rules, integrations, usage, support, deliverables, and payment terms.