Custom AI agent · Finance
AI Accounts Receivable Follow-Up Agent for DTC Brands
Separate open wholesale invoices from marketplace settlement exceptions.
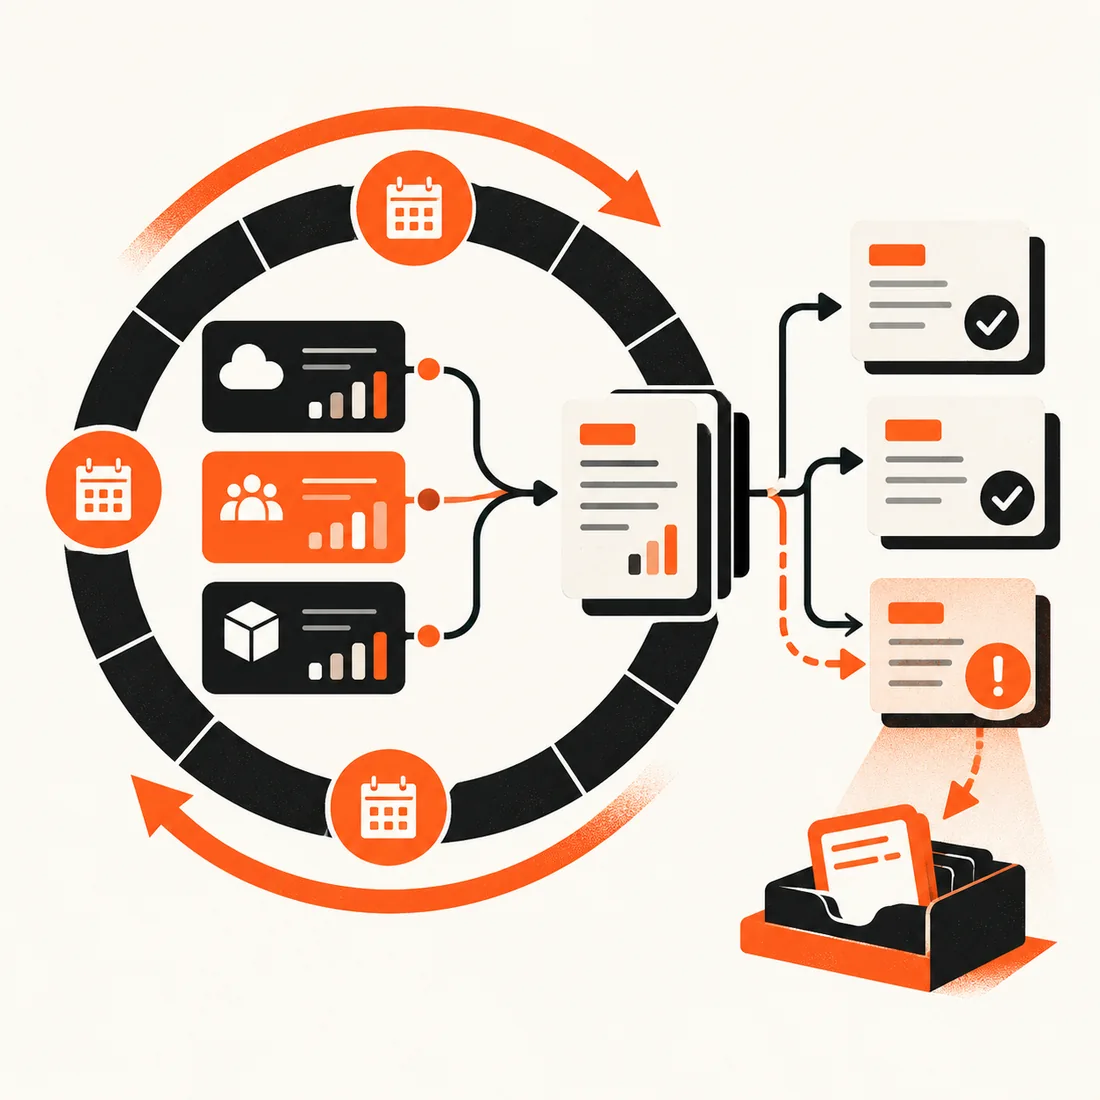
Organize approved retailer invoices and channel-remittance records for DTC finance teams, with deductions, disputes and missing payments routed for review.
- Retailer and wholesale invoices grouped by due date and account
- Marketplace remittance differences linked to source statements
- Deductions, disputes and consumer-payment cases kept in the right review queue
Starting at $300 USD/month
Starting price is $300 USD/month for a tailored solution. Your proposal defines the workflow, deliverables and payment terms. Accounting, commerce or marketplace integrations, channel count, data scope, hosting and ongoing support are scoped before work begins.
What is an AI accounts receivable follow-up agent for DTC brands?
Direct-to-consumer brands may still manage open invoices from wholesale retailers, corporate buyers and channel partners, alongside marketplace or platform remittances that arrive with fees and deductions. This agent organizes approved receivable records by account, invoice or settlement reference, preserves statement dates and flags short payments, missing remittances and disputed deductions for finance review. Consumer checkout, refunds and chargebacks follow separate payment workflows; the team retains control of account outreach, reconciliation and adjustments.
What it can organize across DTC receivables
Track retailer and corporate-buyer invoices
Map approved business account IDs, invoice references, due dates, source-reported balances and payment status into a wholesale receivables workbook. Finance staff verify open amounts and terms in the accounting system before contacting an account.
Reconcile channel settlement statements
Align supplied marketplace or commerce-platform settlement references, statement periods, gross sales, fees, deductions and net payout fields. Flag differences between expected and received amounts with links to the source statement; do not infer why a payout changed.
Route deductions and disputes
Identify records tagged as shortage claims, return allowances, promotional deductions, pricing disputes or pending credits and assign them to the designated owner. The finance or account team validates evidence and decides whether to accept or contest a deduction.
Maintain follow-up history and next steps
Organize approved partner contact dates, account owner, response status, promise-to-pay reference and next review date. A team member confirms the partner context and approves any external follow-up.
Where it can help
Reviewing overdue wholesale invoices
Combine a dated accounting export with approved retailer account and follow-up records, flag invoices with no documented next step and create a finance review queue. Staff confirm balances and terms before contacting the buyer.
Investigating a short marketplace payout
Compare the platform’s settlement statement with the company’s supplied sales and remittance records, list fee or deduction differences and route the case to the channel owner for evidence review.
Separating a retailer deduction from a consumer refund
Classify supplied records by their documented transaction type and route retail-partner deductions to the wholesale owner while consumer refund or chargeback records remain in the designated payment workflow.
How it works
A step-by-step workflow your team can review before launch.
Define which receivables are in scope
Select approved wholesale invoices, corporate-buyer records and channel settlement statements. Explicitly separate individual checkout payments, consumer refunds and chargebacks unless a separately authorized review process is defined.
Map partner, invoice and settlement references
Document account identifiers, invoice and statement periods, currency, due-date conventions, deduction codes and the source of truth for posted payments.
Build the exception and follow-up queue
Transfer supported fields with source references and as-of dates. Flag unmatched accounts, short payments, unexplained deductions, stale statements and missing follow-up history.
Verify and approve finance actions
Finance staff reconcile amounts in accounting and channel systems, gather deduction evidence with account owners, and approve any partner communication, credit or adjustment.
Built around your business
What we configure
- Wholesale retailer and corporate-buyer account identifiers
- Invoice, currency, due-date and posted-payment fields
- Marketplace or platform settlement statement references
- Fee, deduction, allowance, shortage-claim and dispute categories
- Partner owner, prior follow-up and next-review date
- Approved accounting, commerce or marketplace exports after access review
What we need from you
- Sanitized sample wholesale invoices and channel settlement statements
- A source-of-truth decision for balances, currency, posted cash and settlement periods
- Documented deduction codes, partner terms and escalation owners
- A finance reviewer to verify every discrepancy and approve external follow-up
- Clear separation of business receivables from consumer checkout, refunds and chargebacks
Clear boundaries before launch
What it will not do
This agent organizes supplied business receivable and settlement records; it does not charge consumers, issue refunds, reverse payments, decide chargebacks, negotiate retailer terms, determine whether a deduction is valid, approve credits or write-offs, change accounting entries, or independently contact customers or partners. It must not treat a marketplace payout as collected cash until the accounting owner verifies it, or infer a cause for a short payment. Finance staff confirm balances, fees, partner agreements and supporting evidence in the systems of record before communication or adjustment. Consumer payment disputes and personal data require separate authorized workflows.
How success is measured
Compare sampled wholesale invoice and settlement rows with dated accounting and platform statements. Track open-balance mismatches, unlinked remittances, unexplained deductions, missing statement periods, aging exceptions, duplicate partner follow-ups and reviewer correction time. Measure record organization separately from recovery rate, marketplace payout timing, gross margin, cash conversion or consumer satisfaction.
Frequently asked questions
What receivables can this agent organize for a DTC brand?
It can organize approved wholesale-retailer and corporate-buyer invoices, plus marketplace or platform settlement records. The company defines the exact source fields and workflow.
Does it chase individual consumers for payment?
No. Consumer checkout and payment issues follow separate processes. This workflow is designed for business receivables and channel settlements.
Can it reconcile marketplace fees and deductions?
It can line up supplied settlement statement fields and flag differences for review. A finance or channel owner checks fee terms and evidence before accepting or disputing a deduction.
Will it send reminders to wholesale partners?
It can organize prior contact and next-review fields. An authorized employee verifies the account and approves any partner communication.
Can it issue credits or change accounting records?
No. It prepares records and exception queues. Finance staff decide whether a credit, write-off or accounting adjustment is appropriate and make it through authorized systems.
What does the $300/month starting price include?
Tranki solutions start at $300 USD/month. The proposal defines the tailored workflow, deliverables and payment terms. Integrations, channel count, hosting and ongoing support are scoped before work begins.
How do we handle consumer chargebacks or refunds?
Keep them in the brand’s designated, authorized payment workflow. This agent should not decide consumer disputes or issue refunds; any related reporting requires a separately reviewed scope.